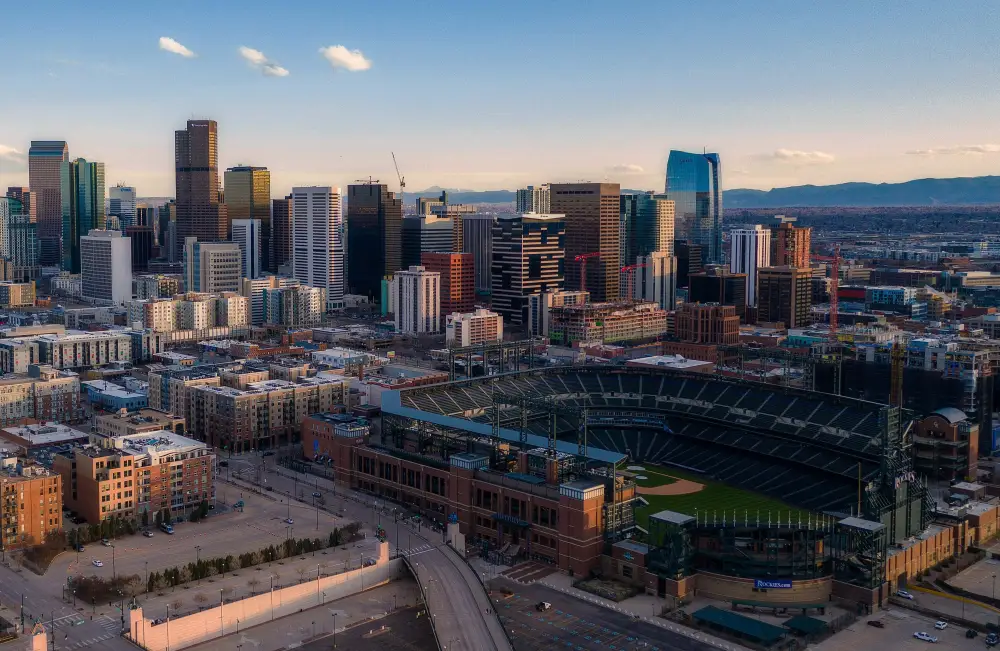
The courthouse
Broomfield County's courts are at the Broomfield Combined Courts, 17 Descombes Dr., Broomfield, CO 80020. Broomfield is part of the 17th Judicial District, which it shares with Adams County.
IT'S MORE THAN MONEY.
Your business sat closed after a covered loss, or your disability benefits were cut off, and the insurer keeps finding reasons not to pay. Colorado lets policyholders challenge an insurer that acts without a reasonable basis. Call (303) 209-9395 and tell us what the insurer has said so far.
No fee unless we winBroomfield, City and County of Broomfield
CGH Injury Lawyers represents Broomfield residents against insurers that deny, delay, or underpay claims without a reasonable basis. Your first conversation with us is free, and we do not get paid unless we win.
Your rent, payroll, and suppliers keep coming due while the insurer reviews your business interruption claim. A Broomfield bad faith insurance lawyer can dig into that review and find out whether the company had a legitimate reason for how long it's taking or what it's refusing.
CGH Injury Lawyers works with Broomfield businesses and families out of our Denver office. The fastest way to reach us is (303) 209-9395, and our contact page is there if you'd rather write.
A business owner in Broomfield might wait months on a business interruption claim while the insurer questions the numbers. A family might have a hail-damaged car or roof paid at a level that doesn't come close to the repair bill.
Disability claims can reach the same point. Benefits arrive for a while, then stop after a file review, and an appeal doesn't change the answer.
Whatever the policy, the statutory test is the same: whether the insurer had a reasonable basis for its conduct. Documents that help us answer quickly include:
Note the date the loss happened, the date you reported it, each date the insurer asked for something, and each date you answered.
Colorado recognizes two claims against an insurer, and they can be pursued together on the same facts. The jury instructions describe the statutory claim as a private right of action that exists "in addition to and separate from" common-law bad faith (Colorado Civil Jury Instructions, ch. 25).
| Statutory claim | Common-law claim | |
|---|---|---|
| Built on | Colorado's insurance code | Travelers Insurance Co. v. Savio, a 1985 Colorado Supreme Court ruling |
| Must be proven | The insurer delayed or denied a covered benefit without a reasonable basis | The insurer acted unreasonably, and knew it or recklessly disregarded it |
| Can lead to | Two times the covered benefit, reasonable attorney fees, and court costs | Compensation for the harm the conduct caused |
The common-law duty
Savio frames the common-law standard as unreasonable conduct combined with knowledge that it was unreasonable or reckless disregard of that fact. It's a two-part showing, and the second part is where these cases get harder.
The statutory duty
A Colorado insurer may not unreasonably delay or deny paying benefits owed to or on behalf of a first-party claimant (C.R.S. 10-3-1115(1)(a)). Subsection (2) defines unreasonable conduct by reference to one thing, the absence of a reasonable basis.
Because the statute doesn't require proof of the insurer's knowledge, it's the easier claim to establish. Among its limits, it excludes claims against another person's liability policy, and it doesn't apply to workers' compensation, title insurance, or life insurance issued under article 7 of Title 10 (C.R.S. 10-3-1115(5), (6)).
The City and County of Broomfield is its own county. The court that hears a suit against an insurer can vary with the facts, including your residence and where the insurer does business.
The courthouse
Broomfield County's courts are at the Broomfield Combined Courts, 17 Descombes Dr., Broomfield, CO 80020. Broomfield is part of the 17th Judicial District, which it shares with Adams County.
Hospital records
When an insurer disputes a medical charge, the treating hospital's records give you something concrete to point to. UCHealth Broomfield Hospital, at 11820 Destination Drive, is shown at Level IV on the Colorado health department's trauma facility list.
Fire district records
North Metro Fire Rescue District serves Broomfield, and its records request page includes an incident report request form. If a fire damaged your home or business, that report may help show where it started.
Examples of Broomfield claims that can stall
We prepare every case as if it will be tried.
Kevin Cheney, Managing Partner of the firm, is an American Board of Trial Advocates member.
We go through your policy, the correspondence, and the timeline of the claim.
Call (303) 835-9177 in Spanish. Our office is at 2701 Lawrence St., Suite 201, Denver, CO 80205.
We work through your coverage, the correspondence, and the claim timeline.
We match what happened to common-law bad faith, the statutory claim, or both.
A written demand goes to the insurer.
Claims-file materials and documentation, plus outside expert input where it helps, such as for a business loss.
That may be the district court for Broomfield County, at the Broomfield Combined Courts, but we confirm the proper court for your facts before filing.
We go after the underlying benefit, statutory damages and attorney fees where they apply.
Recovery depends on the policy, the losses, and what the insurer did. We study the file before we talk about value.
C.R.S. 10-3-1116(1). A first-party claimant whose claim was unreasonably delayed or denied can sue in district court to seek double the covered benefit, plus reasonable attorney fees and court costs. If the insurer pays an unreasonably delayed benefit before judgment, the jury instructions say that payment doesn't reduce the doubled award.
The jury instruction on damages asks jurors to consider:
They're available in some cases. The instructions add that proving bad faith, alone, doesn't establish a punitive damages claim.
Your insurer can question the size of a claim. We compare its position to your records and to any outside input on the loss, and look at whether the insurer had grounds for its figure at the time it chose it.
An insurer can challenge a fairly debatable claim, even if its denial turns out to be a mistake. Under the jury instructions, that factor weighs against bad faith but, without more, is not outcome-determinative, and without a reasonable basis, a claim isn't fairly debatable.
The decision is measured against what the insurer knew when it made it. The jury instructions cite Schultz v. GEICO Casualty Co. as the source of that rule.
An insurer can ask for proof of a loss. When you've sent what was asked for and the file still sits, a dated log of every submission can help show who was waiting on whom.
I wish I could leave more than 5 stars!
Grace Macaluso, 5-star Google review
The jury instructions treat common-law bad faith as a tort governed by C.R.S. 13-80-102. The claim is barred unless it is filed within two years after you knew, or with reasonable diligence should have known, both the injury and its cause.
In Rooftop Restoration, Inc. v. American Family Mutual Insurance Co., the Colorado Supreme Court concluded that the one-year limit on penalty actions under C.R.S. 13-80-103(1)(d) is the wrong limit for a claim brought under section 10-3-1116(1). Because the start of your clock can be contested, have a lawyer confirm the deadline.
If your dispute is over underinsured motorist benefits, the accrual rule is different. A bad faith claim for nonpayment of those benefits can't accrue until you've obtained a judgment against, or settled with, the underinsured driver.
Yes. The statute's definition of first-party claimant includes corporations, associations, partnerships, and other legal entities claiming benefits owed under a policy. A business can bring a bad faith insurance claim in Colorado if its insurer unreasonably delayed or denied covered benefits.
Not automatically. Under the statute, the question is whether the insurer had a reasonable basis for the delay, so we examine what it requested, what you provided, and when.
It can. Disability claims aren't among the statute's exclusions, and a health or disability policy issued in Colorado can't reserve discretion to the insurer to interpret its terms or decide eligibility (C.R.S. 10-3-1116(2)).
Possibly. Under the statute, a first-party claimant whose claim was unreasonably delayed or denied can sue for two times the covered benefit plus reasonable attorney fees and court costs, and a common-law claim can add damages the bad faith caused.
Start by getting a written explanation of how the insurer reached its number. If it had no reasonable basis for paying less than the covered loss, a statutory claim may be available, and we can compare its estimate with your repair bids.
That depends on facts such as where you live and where the insurer does business. For a Broomfield policyholder, the district court for Broomfield County, at the Broomfield Combined Courts, is one possibility.
No. Our office is at 2701 Lawrence St., Suite 201, in Denver, and Broomfield clients work with us from there. Call (303) 209-9395.
It's More Than Money.
Bring what you have, even if it's only a denial letter and a policy number. A bad-faith insurance attorney can tell you what's missing and what the insurer's own file may show. Call (303) 209-9395, or reach us through our contact page.
More reading: our Colorado bad faith insurance lawyer page and the Denver bad faith insurance lawyer page explain the practice in more depth. For crash-related claims, visit the Broomfield pages for car accident lawyers and uninsured motorist lawyers, and for everything else, Broomfield personal injury lawyers.
Prefer to read first? See how Colorado bad faith law works.
CGH Injury Lawyers · 2701 Lawrence St., Suite 201, Denver, CO 80205
Cheney Galluzzi & Howard, LLC, d/b/a CGH Injury Lawyers. Attorney advertising. Past results do not guarantee a similar outcome. Every case turns on its own facts, injuries, and available insurance coverage. This site is for general information and is not legal advice. Reading this page does not create an attorney-client relationship.